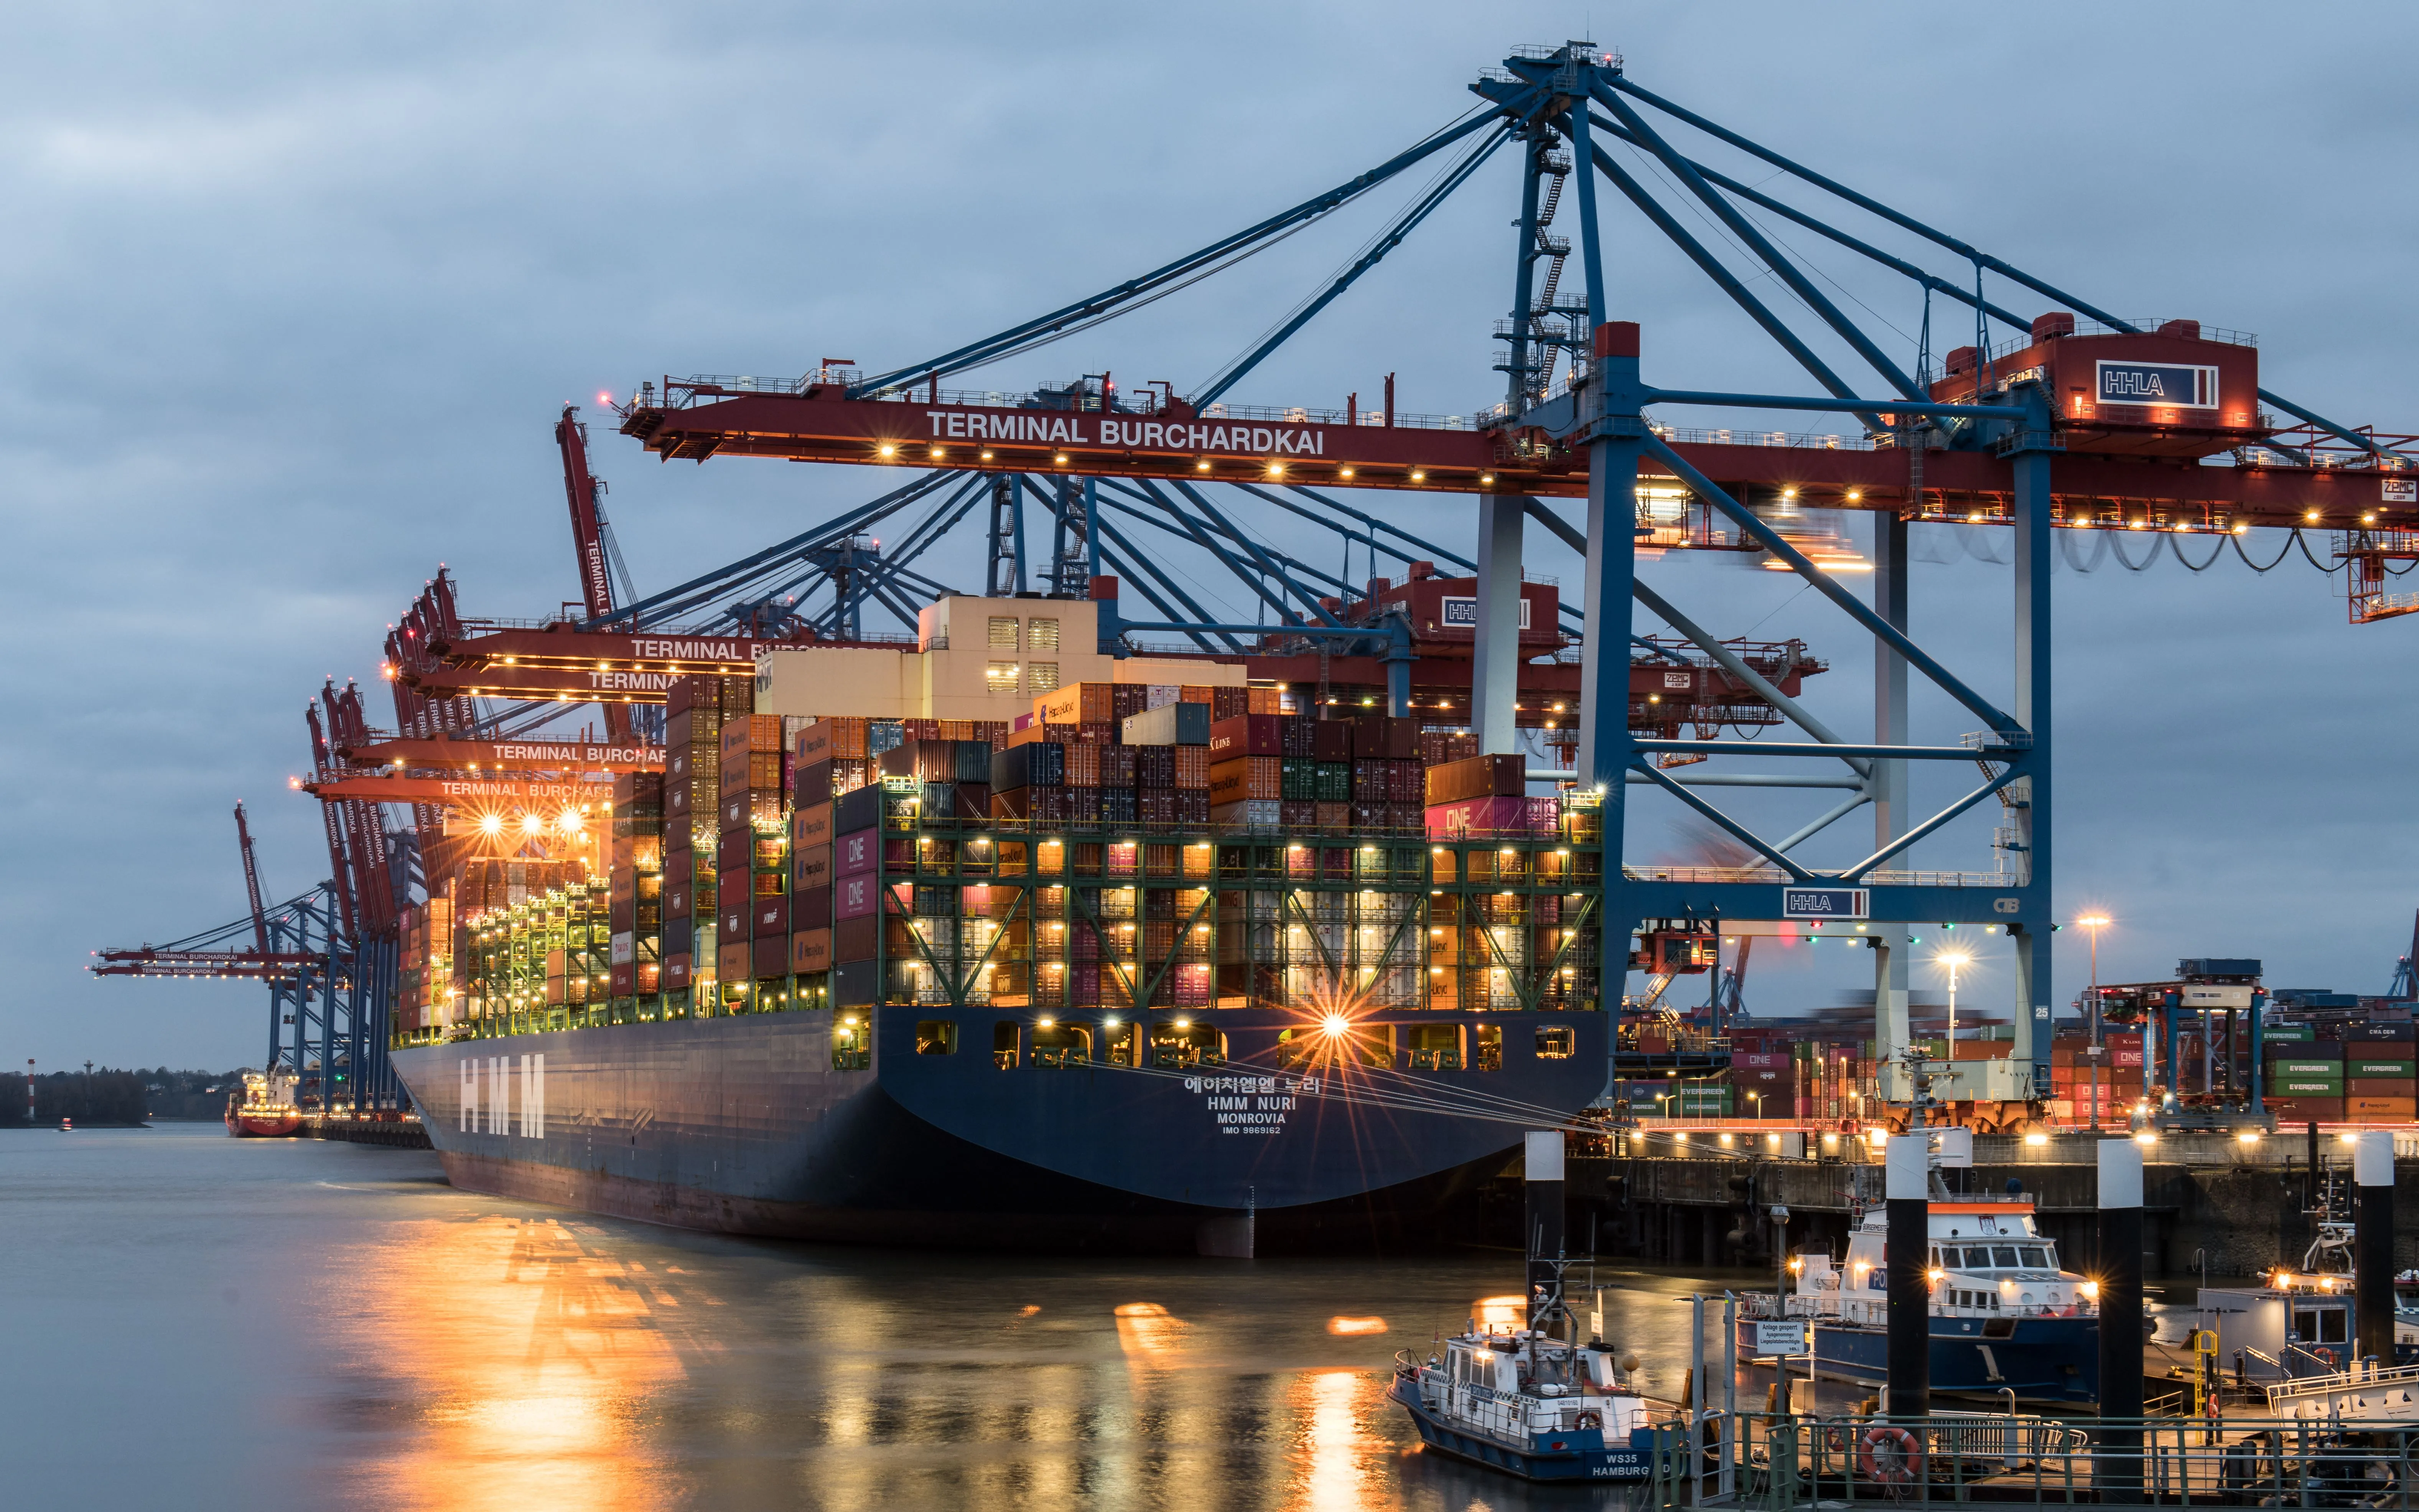
The file a commercial shipment needs at its destination is made of six kinds of document: the transport document (a bill of lading, sea waybill, air waybill, or road or rail consignment note), the commercial invoice, the packing list, proof of origin, certificates and permits for regulated goods, and the importer’s own registration and declaration. What changes from one border to the next is which of them are mandatory, what each one has to say, and which fields are sent to customs as data before the goods arrive.
Summary: this post takes the six one at a time. For each, it sets out what the document is, who issues it, and what the United States, Canada, the European Union, the United Kingdom, Australia, Japan and Mexico ask of it, with a link to the regulator’s or treaty’s own text for each requirement. A table at the end puts the seven destinations side by side. The regulator’s text is the authority at every step; this is a guide to where it is.
The baseline every destination starts from
Two international texts set the frame. The WCO’s Revised Kyoto Convention, in its General Annex, Standard 3.16, says: “In support of the Goods declaration the Customs shall require only those documents necessary to permit control of the operation and to ensure that all requirements relating to the application of Customs law have been complied with.” The WTO’s Trade Facilitation Agreement, in force since February 22nd, 2017, adds that members shall endeavour to accept copies of supporting documents (Article 10.2.1) and shall not demand the exporting country’s export declaration as a condition of import (10.2.3). Footnote 11, attached to that last rule, says nothing in it “precludes a Member from requiring documents such as certificates, permits or licenses as a requirement for the importation of controlled or regulated goods.”
That split shapes everything below. The general documents (transport document, invoice, packing list) are pushed toward the minimum by treaty. The goods-specific layer is left to each country, and in the national rules we read, that layer is where most of the length is.
1. The transport document: bill of lading, sea waybill, air waybill, consignment note
The transport document records the carrier’s acceptance of the goods and where they are going. Which document applies depends on the mode, and so does who makes it out: the carrier, a forwarder, or (for an air waybill) the consignor.
Ocean: bill of lading or sea waybill. Under the Hague-Visby Rules, the carrier “shall, on demand of the shipper, issue to the shipper a bill of lading” showing the leading marks, the number of packages or the quantity or weight, and the apparent order and condition of the goods (Article III(3), as enacted in the UK’s Carriage of Goods by Sea Act 1971). A bill of lading in the 1992 Act’s sense can be transferred by endorsement or, as a bearer bill, by delivery. A sea waybill cannot: the UK’s Carriage of Goods by Sea Act 1992 defines it as a receipt that evidences the contract of carriage and “identifies the person to whom delivery of the goods is to be made by the carrier.” Consolidated cargo usually travels under at least two levels: a master bill from the carrier, and house bills from the forwarder that consolidated it.
Air: the air waybill. The Montreal Convention 1999, which has 145 parties, says that for cargo “an air waybill shall be delivered,” and that “any other means which preserves a record of the carriage to be performed may be substituted” (Article 4). The air waybill must indicate the places of departure and destination and the weight of the consignment (Article 5), is made out by the consignor in three original parts (Article 7), and is “prima facie evidence of the conclusion of the contract, of the acceptance of the cargo and of the conditions of carriage” (Article 11). Article 6 adds that the consignor may be required, “if necessary to meet the formalities of customs, police and similar public authorities,” to deliver a document indicating the nature of the cargo. IATA’s Resolution 672 is the multilateral agreement under which airlines and forwarders use an electronic air waybill in place of paper.
Road: the CMR consignment note. Under the CMR Convention, which has 58 parties, the contract of carriage “shall be confirmed by the making out of a consignment note,” in three original copies, one of which “shall accompany the goods” (Articles 4 and 5). Article 6 lists its particulars, among them a description of the goods and the method of packing, the number of packages and their marks, the gross weight, and “the requisite instructions for Customs and other formalities.” Article 11 puts the customs paperwork on the sender: the sender “shall attach the necessary documents to the consignment note or place them at the disposal of the carrier.” An additional protocol in force since 2011 among its 42 parties gives an electronic consignment note the same effect.
Rail: the CIM consignment note. Under the CIM Uniform Rules, the contract “must be confirmed by a consignment note which accords with a uniform model,” and the note “shall not have effect as a bill of lading” (Article 6). Its particulars include the gross mass, the method of packing, and “a detailed list of the documents which are required by customs or other administrative authorities” (Article 7).
How the destinations use it.
- United States: the transport document is the usual evidence of the right to make entry: “a bill of lading or air waybill, presented by the holder thereof, properly endorsed when endorsement is required,” or a carrier’s certificate (19 CFR 141.11). A non-negotiable bill of lading or air waybill “may not be endorsed by the named consignee to give someone else the right to make entry.”
- Canada: the CBSA’s term is the cargo control document, “a manifest or other control document that acts as the record of a shipment entering, exiting or moving within Canada, e.g. air waybill (AWB)” (Memorandum D3-1-1). Its cargo control number is required on every release: “both electronic and paper release documents require that a CCN be provided” (D17-1-4). Freight forwarders transmit their house bills electronically before arrival for consolidated shipments.
- United Kingdom: the import declaration on CDS references the transport document by type, with a separate code for each: N705 bill of lading, N714 house bill of lading, N740 air waybill, N741 master air waybill, N730 road consignment note, N720 CIM consignment note (GOV.UK, CDS Appendix 5A).
- Japan: the import declaration is accompanied by the “Bill of lading or Sea Way Bill (for import of air cargo : Air Way Bill)” (Japan Customs).
- Australia: an import declaration lodged in person needs the “bill of lading or air waybill” (Australian Border Force).
- Mexico: the information in the bill of lading, packing list or other transport documents that the tax administration requires by rule is transmitted as an annex to the pedimento, the customs entry (Ley Aduanera, Article 36-A).
- Egypt shows how far a destination can reach back into this document: under its Advance Cargo Information system, mandatory since October 1st, 2021, the importer’s ACID number is issued before shipment so that it can be “included in the bills of lading by the foreign exporter” (NAFEZA).
The data that goes ahead of the goods. Before arrival, destinations take a subset of the transport document’s data, plus some invoice data, as an electronic filing, and the filing reaches down to the lowest transport document: the house bill or house air waybill where there is one, as well as the master.
- US ocean (ISF): ten elements “at the lowest bill of lading level (i.e., at the house bill of lading level, if applicable)”: seller, buyer, importer of record number, consignee number, manufacturer or supplier, ship-to party, country of origin, the HTSUS number to six digits, container stuffing location and consolidator (19 CFR 149.3). Eight are due 24 hours before the cargo is laden at the foreign port (149.2).
- US air: the carrier’s advance data carries the air waybill number (“the International Air Transport Association (IATA) standard 11-digit number”), shipper, consignee, quantity, weight and a “precise cargo description”; generic descriptions such as “general cargo” and “STC” (said to contain) “are not acceptable” (19 CFR 122.48a). The Air Cargo Advance Screening data, due before loading, is submitted “at the house air waybill level if applicable” and now includes the consignee’s email and phone number (19 CFR 122.48b; interim final rule).
- Canada: eManifest data is due four hours before arrival by air (or at departure for shorter flights), one hour before arrival by highway (CBSA), and 24 hours before loading for containerized marine cargo loaded outside the US (D3-5-1).
- EU: the entry summary declaration goes through ICS2, operational for all modes since September 1st, 2025, with temporary derogations for road and rail in some member states. For air, the Commission’s guidance says the consignor “as stipulated in the lowest house air waybill” must be given, and must be “different from the carrier, freight forwarder, consolidator, postal operator, or customs agent”; descriptions such as “unknown” are “not acceptable” (European Commission).
- UK: in Great Britain, the carrier is responsible for the entry summary declaration through S&S GB before arrival, including for goods from the EU since January 31st, 2025 (GOV.UK).
2. The commercial invoice
The invoice is the seller’s record of the sale: who sold what to whom, for how much, on what terms, and where customs value is the transaction value, it is the main evidence of the price paid. Of the seven destinations, we found a published list of invoice contents for three (the US, Canada and Mexico); the others define the invoice by what the declaration needs from it.
- United States: 19 CFR 141.86 lists eleven elements (in the appendix below), requires English or an accurate English translation, requires the invoice to “state in adequate detail what merchandise is contained in each individual package,” and requires it to name a responsible employee of the exporter. If the invoice is not available at entry for reasons beyond the importer’s control, CBP may accept a pro forma invoice in the 141.85 format, backed by a bond to produce the real one within 120 days (141.91).
- Canada: Memorandum D1-4-1 splits on value. Above CAD 2,500 value for duty, the Canada Customs Invoice data set is required, supplied by a commercial invoice carrying all of it, a commercial invoice plus a Form CI1 for the missing elements, or a completed CI1 alone. At or below CAD 2,500, a commercial invoice can support the declared value.
- Mexico: the 2026 foreign trade rules set the invoice data for goods worth more than USD 300, including a detailed commercial description, and require that description to be translated into Spanish when it is written in a language other than Spanish, English or French (RGCE 2026, rule 3.1.8).
- Japan: the Customs Act lets Customs require “a written contract, invoice or other documents necessary for confirming the details of the declaration” (Article 68), and Japan Customs lists the invoice first among the documents that accompany the declaration, defining it as “a document describing the name, quantity, and value of the goods” (Japan Customs).
- EU: where customs value is the transaction value, “the invoice which relates to the declared transaction value is required as a supporting document” (Commission valuation guidance), and supporting documents “must be available on request by the Customs Authority” (European Commission). We found no EU-level list of invoice fields.
- UK: the importer “must keep records of commercial invoices and any customs paperwork” (GOV.UK), and a transaction-value declaration on CDS typically references the invoice with code N935 (GOV.UK). We found no HMRC list of invoice fields; HMRC lists the valuation evidence it may ask for instead.
- Australia: commercial invoices are among the documents needed to lodge an import declaration in person (Australian Border Force).
Freight and insurance: where the invoice stops and other documents start. Destinations disagree on whether international freight and insurance belong in customs value, which decides whether freight and insurance documents matter to the declaration.
- The EU adds “the cost of transport and insurance of the imported goods” up to the place where they enter the customs territory (Union Customs Code Article 71(1)(e), quoted in the Commission’s valuation compendium). Mexico includes transport and insurance in the transaction value as well (Ley Aduanera, Article 65), and Japan Customs lists the insurance certificate and the freight account among the documents that accompany the declaration.
- Canada goes the other way: value for duty deducts the cost of transport and insurance from the place in the country of export from which the goods are shipped directly to Canada (Customs Act, section 48(5); D13-4-7).
- The US invoice must itemize “all charges upon the merchandise … including freight, insurance, commission” (141.86(a)(8)).
Attestation. Some destinations require the invoice to be legalised or attested, and the Apostille Convention does not apply “to administrative documents dealing directly with commercial or customs operations.” The United Arab Emirates moved this step to the destination: since February 1st, 2023, electronic attestation is mandatory for goods imported into the UAE valued at AED 10,000 and above, with a 14-day grace period from the bill of entry date to pay the fee before a fine of AED 500 per invoice applies (UAE Ministry of Foreign Affairs), and the UAE Embassy in Washington stopped processing commercial invoices on the same date.
3. The packing list
The packing list is the shipper’s record of what is in each package: counts, contents, weights, marks. Japan’s customs guidance lists it as a standard attachment, and Mexico transmits the packing list information its rules require with the entry. In the US and Canada its content is required on the invoice and the separate list is conditional or not mentioned. The UK requires it in some cases, and in the EU we found no requirement for it as a separate document.
- United States: release requires “a packing list, where appropriate” (19 CFR 142.3), and the invoice itself must state what is in each package and the marks and numbers of the packages (141.86). The paragraph of 141.86 that carries the per-package rule is titled “Packing list.”
- Canada: we found no CBSA requirement for a separate packing list. The package data is part of the Canada Customs Invoice: the number and kind of packages, their marks and numbers, and net and gross weight (D1-4-1, Appendix A).
- Japan: the packing list is among the documents that accompany the import declaration (Japan Customs).
- Mexico: the information in the bill of lading, packing list (“lista de empaque”) or other transport documents that the tax administration requires by rule is transmitted as an annex to the pedimento (Ley Aduanera, Article 36-A).
- UK: CDS has a code for referencing a packing list (N271) in the declaration, and HMRC’s code list notes that it is a mandatory document in some cases (GOV.UK).
- EU: we found no Commission page listing the packing list as a required supporting document.
- Australia: the 2013 guide to documentary import declarations, still hosted by the ABF, refers to packing lists among the commercial documents to consult and to present “if requested” (Australian Border Force).
4. Proof of origin
Origin is declared on every entry. A separate proof of origin is needed when the importer claims a lower duty rate under a trade agreement, and can also be needed when a duty depends on origin, as a 2026 Canadian measure at the end of this section shows. A Recommended Practice in the Kyoto Convention’s optional origin annex states the principle: documentary evidence of origin “should be required only when it is necessary.” The form is set by each agreement, not by the destination.
- USMCA / CUSMA / T-MEC: a certification of origin completed by the importer, exporter or producer, with no prescribed format. In the US it “may be provided on an invoice or any other document” (though not an invoice issued in a non-USMCA country) and “must be in the possession of the importer at the time the claim” is made (19 CFR 182.12). Canada lists nine minimum data elements (CBSA) and does not require a certification where the value for duty does not exceed CAD 3,300, with conditions (CBSA). Mexico’s Secretaría de Economía states that the certification can go on the invoice or any other commercial document and is valid for four years (Secretaría de Economía).
- EU agreements: the Commission describes three common routes: an EUR.1 or EUR-MED movement certificate; a statement on origin made out by the exporter on the invoice or another commercial document, by an exporter registered in REX or, without registration, for consignments up to EUR 6,000 (ex-works); and importer’s knowledge, named for the agreements with Japan, New Zealand and the UK.
- UK agreements: under the UK-EU Trade and Cooperation Agreement, a statement on origin on the invoice or another document, or importer’s knowledge (GOV.UK); under the UK’s other agreements, an origin declaration, an EUR1 or EUR-MED certificate, importer’s knowledge in some agreements, and a Form A under the Developing Countries Trading Scheme (GOV.UK).
- Japan’s economic partnership agreements: a certificate from the exporting country, an origin declaration by an approved exporter, or an origin certification by the importer, exporter or producer, depending on the agreement (Japan Customs).
- Australia, China-Australia FTA: a declaration of origin may replace a certificate of origin only where the goods are covered by a valid origin advance ruling; otherwise “a valid Certificate of Origin must be held at the time of importation” (Australian Border Force).
- RCEP: three forms: a certificate of origin from an issuing body, a declaration by an approved exporter, and a declaration by an exporter or producer, the last phased in within 10 years of entry into force (20 for Cambodia, Lao PDR and Myanmar), with a possible extension of up to 10 more. A proof of origin is valid for one year.
When origin decides the duty without any preference claim. Canada’s United States Surtax Order (2026), in effect since September 8th, 2026, applies a surtax of 15, 25 or 50 percent to listed goods originating in the United States, and the notice says that for commercial goods, proof of origin may take the form of a commercial invoice or any other document containing the CUSMA minimum data elements.
5. Certificates, permits and declarations for particular goods
This is the layer the Trade Facilitation Agreement leaves to each country, and it attaches to the goods, not to the route. It is also the longest. Grouped by what the document is for:
Food, animals and plants.
- US: FDA prior notice for food, no less than 2 hours before arrival by road, 4 by rail or air, 8 by water (21 CFR 1.279); an APHIS permit for fruits and vegetables, with exceptions (7 CFR 319.56-3); a phytosanitary certificate for plants for planting (7 CFR 319.37-6).
- Canada: the CFIA’s Automated Import Reference System gives the requirements for regulated goods, and food imports need a Safe Food for Canadians licence.
- EU: a Common Health Entry Document in TRACES for goods subject to border checks (European Commission); a phytosanitary certificate for listed plants and plant products, with pineapples, coconuts, durians, bananas and dates exempt (European Commission); a flag-state catch certificate for marine fishery products, filed through CATCH since January 10th, 2026 (European Commission).
- UK: IPAFFS pre-notification for animal products from the EU at every risk level, and a health certificate for medium and high-risk ones (GOV.UK); a phytosanitary certificate for each consignment of high and medium-risk plants and plant products, with medium-risk fruit and vegetables from the EU temporarily treated as low risk (GOV.UK), an easement extended to January 31st, 2027. A UK-EU agreement the government intends to take effect in mid-2027 would remove export health certificates for EU goods.
- Japan: an import notification under Article 27 of the Food Sanitation Act for food, additives, apparatus and containers or packaging imported for sale or business use (Ministry of Health, Labour and Welfare).
- Australia: whether a commodity needs a permit, treatment or supporting documents is set in the department’s BICON system.
Wood packaging and containers. ISPM 15 covers wood packaging material in international trade, dunnage included, and excludes processed wood such as plywood; the treatment mark on the wood “renders the use of a phytosanitary certificate unnecessary” (ISPM 15), under a convention with 185 contracting parties. The US applies it in 7 CFR 319.40-3; Canada applies it with an exemption from treatment and marking for wood packaging coming directly from the continental United States and made entirely of US or Canadian wood (D-98-08). Australia adds a document of its own for sea containers: a packing declaration, “a document issued by the packer of a sea container attesting to the type of packing materials used in the container,” with a cleanliness statement for full container loads (Department of Agriculture).
Dangerous goods. The consignor gives the carrier the dangerous goods information on a dangerous goods transport document or, with the carrier’s agreement, electronically. At sea, the IMDG Code requires the document to show the UN number, the proper shipping name, the hazard class, any subsidiary hazard and the packing group, in that order, and to include a declaration signed and dated by the consignor that the goods “are fully and accurately described” and “classified, packaged, marked and labelled/placarded” (IMDG Code, Amendment 42-24, 5.4.1). US rules require the same description, in that sequence (49 CFR 172.202), printed in English (172.201), and a signed shipper’s certification, for which the IMDG wording is one accepted form; for air, the certification is provided in two copies with an added statement that the air transport requirements have been met (49 CFR 172.204).
Product safety and conformity.
- US: CPSC certificate of compliance data, eFiled in ACE at entry since July 8th, 2026 (January 8th, 2027 for goods entered from a foreign-trade zone) (final rule); a TSCA positive or negative certification for chemicals before release (19 CFR 12.121); an import declaration for motor vehicles and equipment (49 CFR 591.5); for radio-frequency devices, a determination that the device meets an FCC entry condition, with documentation produced on request for a year after entry (47 CFR 2.1203).
- EU: CE marking and an EU declaration of conformity, which the manufacturer issues; importers “must have knowledge of the legal requirements and ensure that products they distribute or import meet them” (European Commission).
- Mexico: proof of compliance with non-tariff regulations, such as the NOM technical standards, is transmitted with the pedimento (Ley Aduanera, Article 36-A).
- Conformity certificates before shipment: Saudi Arabia’s SABER platform requires each product to be registered with a product conformity certificate or a self-declaration before the importer can request a shipment certificate. Nigeria’s SONCAP is “a pre-shipment verification of conformity to Standards process”; its product certificate opens the Form M with the central bank, and its SONCAP certificate is used for clearance at the port. The TFA bans required pre-shipment inspection only for tariff classification and customs valuation (Article 10.5.1); for other kinds, Article 10.5.2 only encourages members not to add new requirements. Our read is that conformity programmes like these fall under 10.5.2 rather than the ban, because they verify product standards.
Environmental and trade measures.
- CITES species: CITES permits; in the EU under Regulation 338/97.
- US Lacey Act: a declaration for plant and wood products on the phase-in list, only accepted electronically since January 1st, 2026.
- EU CBAM (iron and steel, aluminium, cement, fertilisers, hydrogen, electricity): since January 1st, 2026 the importer must be an authorised CBAM declarant, unless it imports less than 50 tonnes a year of goods other than hydrogen and electricity, and customs checks the authorisation before release (European Commission Q&A, Commission news).
- EU deforestation regulation: from December 30th, 2026 for large and medium operators, and June 30th, 2027 for most micro and small ones (European Commission), the customs declaration must carry the reference number of the due diligence statement (European Commission).
6. The importer’s own registration and declaration
The last part of the file is the importer’s: an identity with the customs administration, set up once, and a declaration for each shipment, which a broker or agent can make on the importer’s behalf.
- United States: a single-entry or continuous bond on CBP Form 301 before a formal entry is released (19 CFR 142.4); formal entry applies above USD 2,500 (143.21). The entry is CBP Form 3461 or its electronic equivalent (142.3), followed by the entry summary, CBP Form 7501, “within 10 working days after the time of entry” (142.12). Duty-free de minimis treatment has been suspended for all countries since August 29th, 2025, and low-value non-postal shipments now “must utilize formal or informal entry procedures” (CBP interim final rule).
- Canada: registration in CARM, the system of record since October 21st, 2024, where the Commercial Accounting Declaration replaced the B3 and B2. Since May 20th, 2025, release before payment requires the importer’s own financial security (Customs Notice 24-27). Under Memorandum D17-2-5, in effect since January 1st, 2026, whoever is declared importer of record, including a broker that declares itself, is the primary liability holder for the duties, jointly liable with the importer and owner. The release data includes the importer’s business number and the 10-digit HS code for each line (D17-1-4).
- EU: an EORI number, “mandatory for the clearance of all types of customs operations in the customs territory of the EU” (European Commission), and a customs declaration in the member state’s system. The separate DV1 valuation form has been replaced by declaration data elements: Irish guidance says a declaration data element replaces it, and Spanish guidance maps its content to data elements of the declaration.
- UK: an EORI number starting with GB, and possibly one starting with XI for goods moving to or from Northern Ireland (GOV.UK), and an import declaration on CDS, which an agent established in the UK can make on the importer’s behalf (GOV.UK).
- Australia: an Import Declaration when a consignment has “a combined value of over AUD1,000” and is cleared into home consumption, made by the importer or a licensed customs broker, with documents kept for five years; for air and sea cargo at or below that value, a Self-Assessed Clearance declaration (Australian Border Force).
- Japan: an import declaration of “the cargo’s product name, its quantity and price” (Customs Act, Article 67).
- Mexico: registration in the Padrón de Importadores and an electronic pedimento (Ley Aduanera, Articles 59 and 36), usually filed by a customs broker, though importers may clear goods themselves (Article 40). The importer also files a value declaration (manifestación de valor) under oath for each transaction; an amendment published on September 22nd, 2026 let importers use the earlier transitional rules for it until September 30th, 2026, and kept some documentation relaxations until December 31st, 2026.
The seven side by side
| Transport document | Commercial invoice | Packing list | Proof of origin (preference) | |
|---|---|---|---|---|
| United States | B/L or AWB as evidence of the right to make entry (141.11); ISF and air advance data at house level | 11 elements (141.86), in English | “Where appropriate” (142.3); per-package contents on the invoice | USMCA certification, no prescribed form |
| Canada | Cargo control document; CCN on every release | CCI data set above CAD 2,500 (D1-4-1) | Package count, marks and weights on the CCI | CUSMA certification, not required up to CAD 3,300 |
| European Union | ICS2 entry summary (master and house level for air) | Supporting document for transaction value; no EU field list found | No EU-level requirement found | EUR.1, statement on origin (REX), or importer’s knowledge |
| United Kingdom | Referenced by type on CDS (N705, N740, N730, N720) | Kept as a record; referenced as N935 (or N325) | Code N271; mandatory in some cases | Statement on origin or importer’s knowledge (TCA) |
| Australia | B/L or AWB to lodge a declaration in person | Commercial invoices to lodge a declaration in person | Presented if requested | Depends on the agreement (ChAFTA: certificate unless an advance ruling) |
| Japan | B/L or sea waybill; AWB for air | Accompanies the declaration; may be required (Art. 68) | Accompanies the declaration | Certificate, approved exporter, or self-certification, by agreement |
| Mexico | Data annexed to the pedimento | CFDI or equivalent above USD 300; description in Spanish, English or French | Data annexed to the pedimento | T-MEC: certification on the invoice or any commercial document |
Certificates for regulated goods and the importer’s registration vary too much by product to fit a cell; sections 5 and 6 carry them.
Appendix: the US invoice elements in 19 CFR 141.86(a)
- The port of entry.
- The time, place and parties of the sale, or, if the goods were not sold, when, where and by whom they were shipped.
- A detailed description of the merchandise, including the name by which each item is known, the grade or quality, and the marks and numbers of the packages.
- Quantities.
- The purchase price of each item in the currency of the purchase.
- The value, if the goods were not purchased.
- The kind of currency.
- All charges on the merchandise itemized by name and amount, including freight, insurance and commission.
- Rebates, drawbacks and bounties.
- The country of origin.
- Assists, such as dies, molds, tools and engineering work, not included in the invoice price (those furnished in the US are excluded).
CargoLint reads the commercial invoice, packing list, ocean bill of lading and certificate of origin and cross-checks them against each other, the comparisons described in What Customs Actually Checks. To see what it finds on your own paperwork, run a recent shipment through the free trial.
CargoLint provides document automation software, not customs brokerage or legal advice. The requirements summarized here were read from the regulators’ and treaties’ own text in October 2026, are linked at each point, change on each administration’s own schedule, and carry conditions and exceptions this post does not reproduce. How they apply to a particular shipment is a question for your broker or the destination authority.